Texas Capital Securities Shifts Rating on Melco Resorts & Entertainment
Skriven av Sage Schröder · 2026-10-17
Texas Capital Securities Shifts Rating on Melco Resorts & Entertainment
Texas Capital Securities has adjusted its position on Melco Resorts & Entertainment by moving the rating from Buy to Hold while lowering the price target from $8, a change tied directly to persistent pressures in the Macau gaming sector as of October 2026. This adjustment marks the latest development in financial coverage of casino operators with significant exposure to Asian markets.
Details of the Rating Change
The firm issued the downgrade after evaluating current performance metrics and forward-looking indicators for Melco Resorts & Entertainment, whose operations center on integrated casino resorts in Macau. Reports indicate the price target revision reflects measured expectations rather than any sudden operational failure, and analysts have connected the move to broader patterns in visitor volumes and revenue generation across the region. Observers note that such adjustments often follow quarterly data releases and regulatory updates from Macau authorities, which continue to shape the operating environment for foreign-invested gaming companies.
Macau Market Conditions in Focus
Macau remains the primary revenue driver for Melco Resorts & Entertainment, and recent months have shown uneven recovery trajectories when compared with pre-pandemic benchmarks. Data from industry monitoring groups shows fluctuations in table games hold percentages alongside shifts in mass-market visitation, factors that Texas Capital Securities cited as contributing to the revised outlook. While certain operators have reported incremental gains in non-gaming amenities such as hotel occupancy adn retail leasing, the core gaming segment continues to face headwinds from regional economic conditions and travel patterns originating from mainland China.
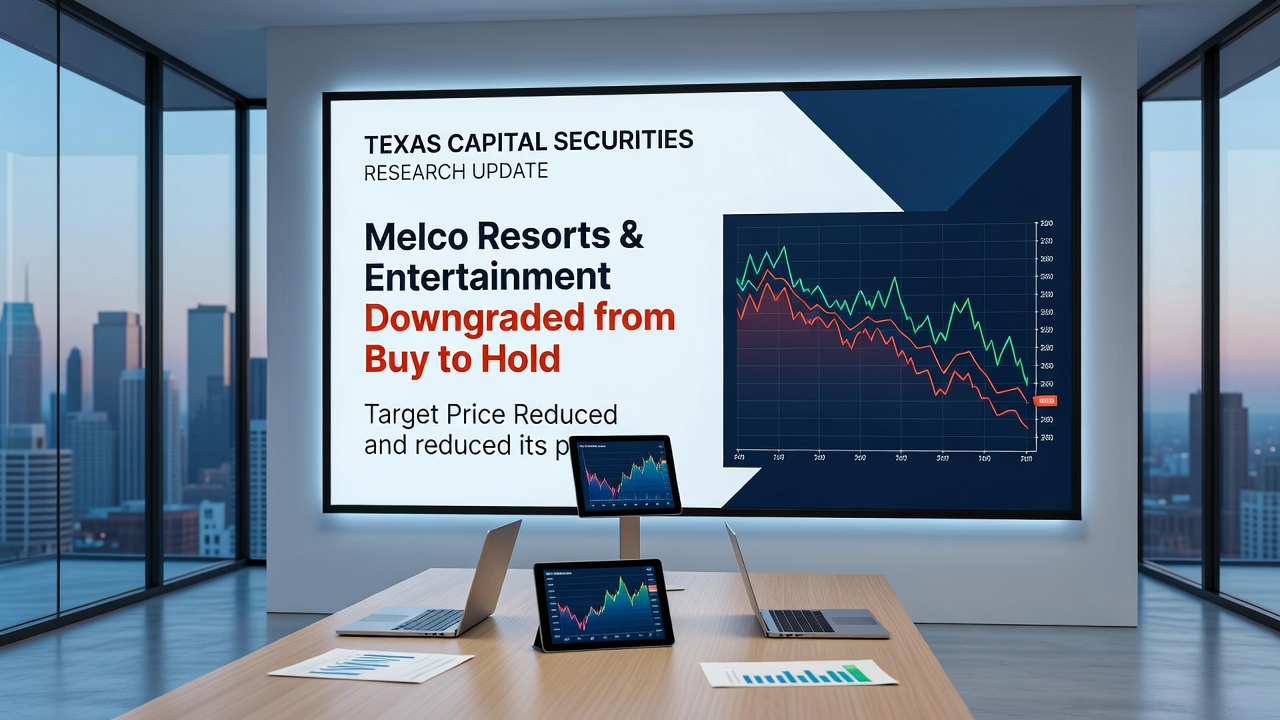
Those monitoring cross-border tourism statistics point out that visa policy adjustments and economic sentiment in source markets can influence arrival numbers within weeks, creating short-term volatility that rating agencies must incorporate into their models. The downgrade therefore aligns with a pattern seen across several research desks that cover Macau-exposed equities, where Hold ratings have become more common when growth assumptions are tempered.
Company Profile and Geographic Exposure
Melco Resorts & Entertainment operates multiple properties under the City of Dreams and Studio City brands, each combining gaming floors with extensive hospitality and entertainment offerings. The company maintains its listing on major exchanges, which subjects it to standard disclosure requirements and allows investors to track key performance indicators such as adjusted property EBITDA and rolling chip volume. Because Macau accounts for the overwhelming majority of its earnings, any sustained change in local market dynamics tends to register quickly in analyst reports and institutional positioning.
Financial filings reveal that capital expenditure plans for facility upgrades and new attractions remain in place, yet the pace of return on those investments now faces closer scrutiny from firms like Texas Capital Securities. Investors following the stock have seen similar rating actions from other houses in prior cycles when macroeconomic signals from the Greater Bay Area region turned mixed.
Broader Context for Gaming Sector Analysts
Securities research in the casino space often weighs regulatory developments in both host jurisdictions and the home countries of listed operators. In this instance, the downgrade arrives alongside ongoing commentary from Macau's gaming regulator regarding licensing compliance and responsible gaming measures, elements that can affect operating costs and marketing flexibility. Industry associations tracking global gaming trends have documented how such regulatory layers interact with consumer demand cycles, producing the kind of data points that feed directly into price target calculations.
Market participants tracking Melco Resorts & Entertainment through October 2026 will likely compare this latest note against upcoming earnings releases to assess whether the Hold rating anticipates further downside or simply signals a period of consolidation. Historical patterns show that rating changes of this nature can influence short-term trading volumes even when the underlying business fundamentals remain stable.
Conclusion
The Texas Capital Securities downgrade of Melco Resorts & Entertainment from Buy to Hold, accompanied by the reduced price target, provides a clear illustration of how analyst models incorporate Macau-specific variables into equity recommendations. As additional data emerges from both the operator and the local gaming authority, market observers will continue to evaluate whether current valuations adequately reflect the balance between near-term challenges and longer-term infrastructure investments. This single adjustment adds to the record of coverage updates that shape institutional views on companies with concentrated exposure to one of the world's largest gaming markets.